
Tax-Mitigation Strategies
Explore Rendio's category-level education across major tax-advantaged strategies. Each overview covers how the strategy works, key tax characteristics, and general planning considerations.
This content is product-agnostic and designed to help tax advisors build general knowledge of these strategies for more effective client conversations.
-
Charitable Donations
Fee Simple Donation Strategies
Charitable donation strategies allow taxpayers to contribute appreciated real estate, artwork, and other non-cash assets to qualified charitable organizations while potentially receiving an income tax deduction based on fair market value.
-
Oil & Gas
Intangible Drilling Cost Deductions & Working Interest Tax Benefits
The U.S. tax code has long provided favorable treatment for oil and gas development, including accelerated deductions for intangible drilling costs and tax-advantaged treatment of working interest income.
-
Green Energy
Investment Tax Credits & Renewable Energy Incentives
The U.S. tax code provides federal tax incentives designed to encourage the development of renewable energy infrastructure, including solar, energy storage, and other qualifying systems. These incentives may include investment tax credits based on qualifying project costs, along with accelerated and bonus depreciation on eligible equipment.
-
Short-Term Rentals
Cost Segregation & Material Participation Tax Strategy
Short-term rental may provide access to accelerated depreciation and potential active income offset when properly structured.
-
Real Estate
Depreciation, Cost Segregation & Capital Gain Planning Strategies
Real estate may provide tax advantages through depreciation, cost segregation, bonus depreciation, and capital gain planning strategies. Individuals may be able to accelerate deductions on qualifying property components while also using planning tools such as IRC §1031 exchanges to defer gain.
-
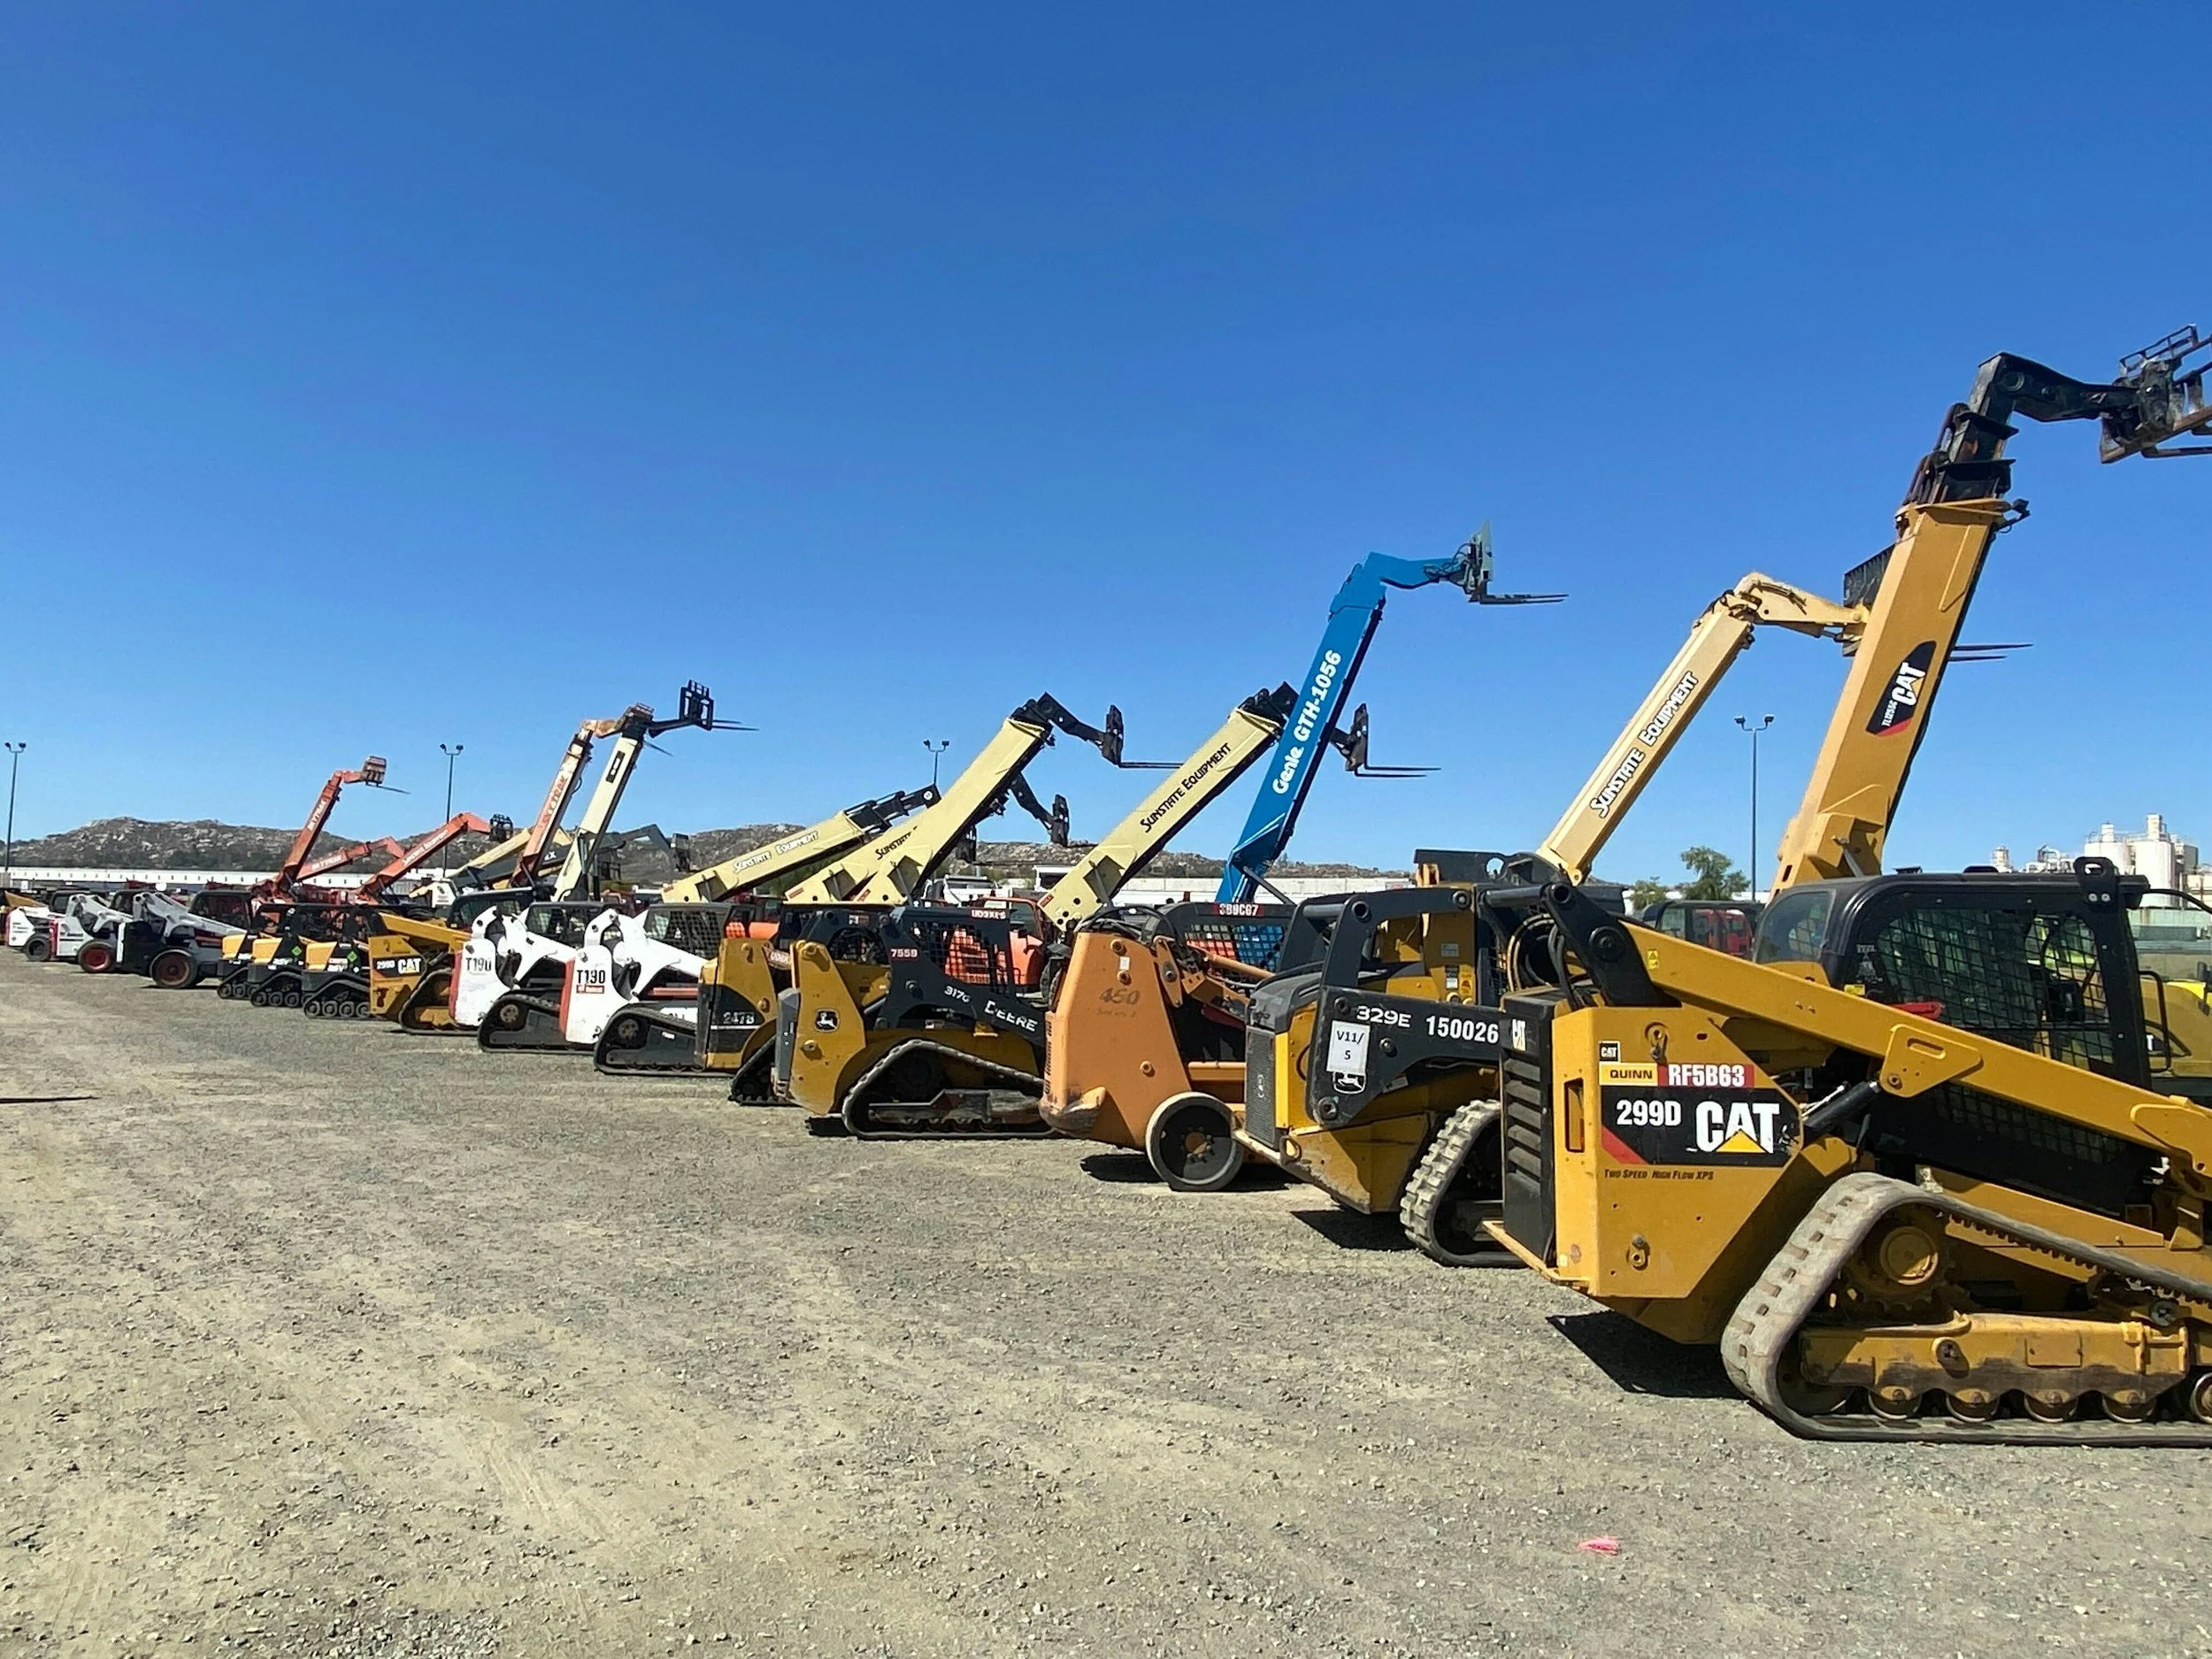
Equipment Leasing
Depreciation-Based Income & Asset Financing Strategies
Equipment leasing structures involve physical assets leased to operating businesses, with lease income taxed to the asset owner and depreciation — including potential bonus depreciation — used to offset that income over time. The tax code's treatment of depreciation recovery is central to how these structures are evaluated from a planning perspective.
-
Movie Production Tax Credits
State Incentives & Transferable Credit Strategies
Movie production tax credit strategies are designed around state incentive programs that encourage film, television, and media production within specific jurisdictions. These programs may provide state-issued credits based on qualified production expenditures, with credit usability, refundability, and transferability.
-
Qualified Opportunity Zones
Capital Gain Deferral & Long-Term Appreciation Strategies
Qualified Opportunity Zone (QOZ) were established to encourage long-term capital investments in designated economic development areas across the United States.
-
Roth Conversions
Tax Rate Arbitrage & Tax-Free Retirement Income Strategies
Roth conversion strategies allow taxpayers to move assets from traditional retirement accounts into Roth accounts by recognizing taxable income in the year of conversion. This may allow future growth and qualified withdrawals to be received tax-free, creating long-term flexibility for retirement income and tax bracket management.
-
Cash Balance Plans
High Contribution Retirement Strategies for Tax Deferral
Cash balance plans are employer-sponsored defined benefit retirement plans that may allow business owners and high-income professionals to make larger deductible retirement contributions than traditional defined contribution plans. Contributions are generally determined through actuarial calculations, may be deductible to the business under applicable retirement plan rules, and grow tax-deferred until distribution.
-
Micro Captive Insurance (831b)
Risk Management Structures & Tax Election Considerations
Micro captive insurance arrangements allow qualifying businesses to insure specific business risks through a captive insurance company. An eligible non-life insurance company may elect to be taxed on taxable investment income rather than underwriting income.